Half of 2024 has passed. During this period, despite the persistent low prices and overcapacity in the anode materials market, the early surge in downstream demand has invigorated the anode market in H1. For companies, the past six months have been complex. In the same market environment, different expectations and strategies led to varied choices and outcomes. In my view, "significant growth and structural changes" best describe the anode market in H1.
According to SMM, in 2024H1, China's graphite anode materials production reached 816,400 mt, up 9.6% YoY.
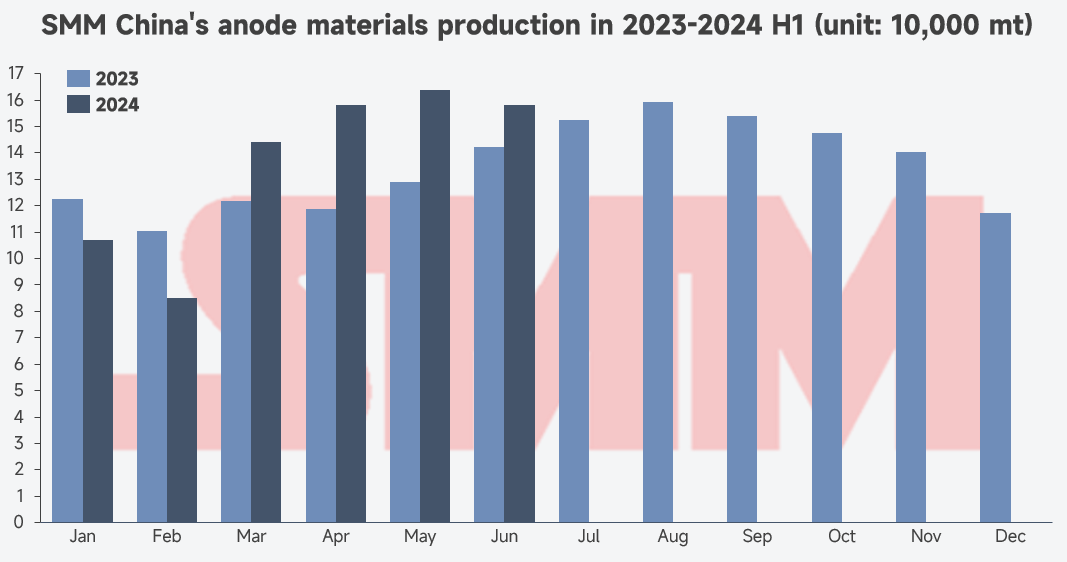
In 2024H1, BTR maintained its leading position in the anode materials industry, with a total share of about 25%. Due to varying predictions on the duration of the anode market downturn and differences in companies' finances, inventory, and market focus, the strategic routes chosen by leading companies diverged significantly, altering the industry's "three major" structure.
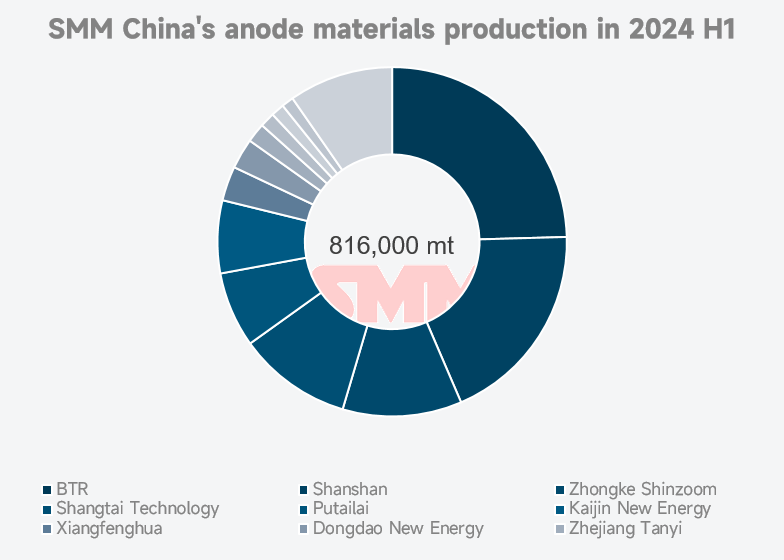
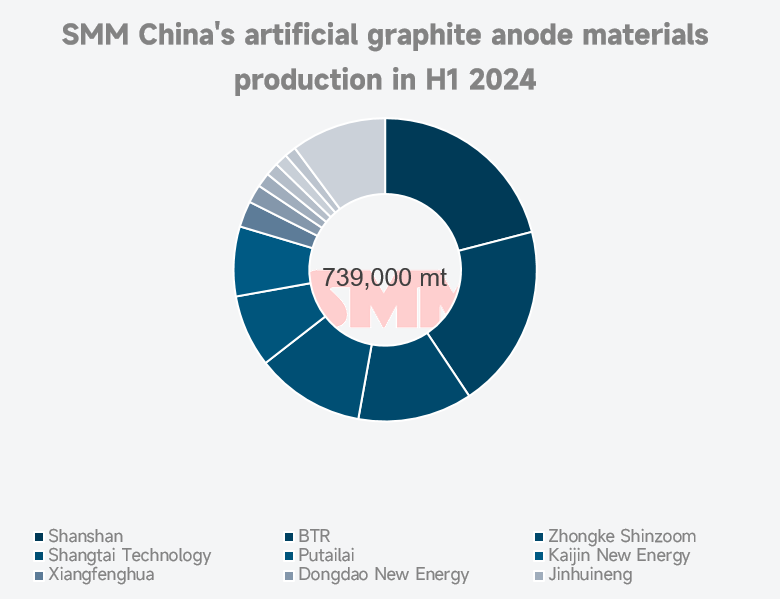
In 2024H1, with the continued weakness in raw material and graphitization costs, artificial graphite anodes still had a clear cost and price advantage. Meanwhile, as natural graphite exports were strictly controlled by the graphite bill, overall demand weakened. Additionally, the production and sales growth of silicon-based and hard carbon anode products was lower than expected, further increasing the market share of domestic artificial graphite anodes. According to SMM, in 2024H1, China's artificial graphite anode production was 739,000 mt, accounting for about 91%, up 11% YoY. Shanshan continued to dominate the artificial graphite materials industry, with a total share of about 21%.
End-users' performance requirements for anode materials also contributed to the increased share of artificial graphite anodes. NEV sales saw significant growth in H1, and power battery cells demanded higher performance in fast charging. Leading companies, leveraging their technical advantages, captured the fast-charging anode materials market. Shanshan and BTR maintained top positions, while Zhongke Shinzoom and Shangtai Technology also saw an increase in their shares. Energy storage sector, as the market heated up, the iteration of 314Ah batteries also raised higher specifications for energy storage anode materials. New entrants like Sunrise New Energy seized the development opportunities in the energy storage market, actively responded to new product demands from customers, and significantly increased their shipments and industry share.
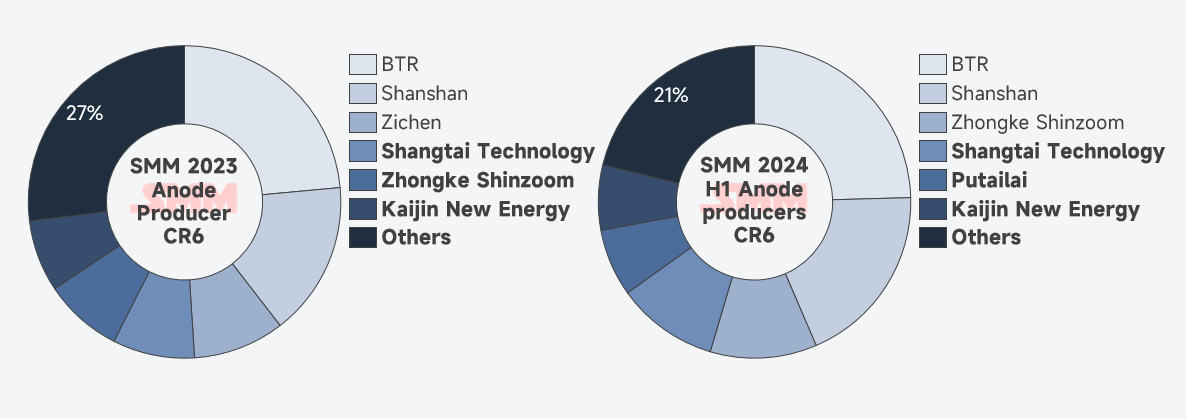
In 2024H1, industry concentration continued to rise, with CR6 reaching 78%. In the current context of limited cost and price reduction room for anodes, downstream customers are more focused on "quality" and "stable supply" rather than "low prices." For battery cell manufacturers, anode companies that can timely respond to customer needs and ensure quality and quantity in supply are more worthy of selection than those offering merely low prices. For anode companies, this is not only the "confidence" to maintain product quality and scale amid the market downturn but also raises higher requirements for controlling production processes.
Looking back, although there was significant growth in 2024H1, the anode industry still faces persistent issues, and it cannot be considered a "spring bloom." The demand highlight may even fade in Q3 as downstream enthusiasm cools. However, the industry downturn is not entirely without benefits for companies: optimizing and upgrading product structures, managing inventory and finances, and improving the upstream and downstream chains are perpetual challenges that become even more crucial now. While industry and supply chain prosperity are essential for company growth, when the "wind" weakens, only strong "internal improvement" can ensure higher and more stable standing.